
By Daniel Morris, Chief Market Strategist
Away from European bond markets, the major story for equity markets has been renewed volatility in emerging market (EM) semiconductor and technology hardware stocks. An index of these companies has dropped back towards the lows of late July, though they are still 1.8% above that level. This leaves them 28% below the July peak but with a year-to-date gain of 47%.
While the declines from the highs are unfortunate, this level of volatility should not be surprising. Estimates of the impact of the artificial intelligence phenomenon on the economy and on corporate profits range widely. This can be seen in the rising standard deviation of estimates for EM tech hardware stocks, which has jumped from 10 at the beginning of the year to 82 today. By contrast, the variation for non-tech stocks has stayed constant at around five (see Exhibit 1).
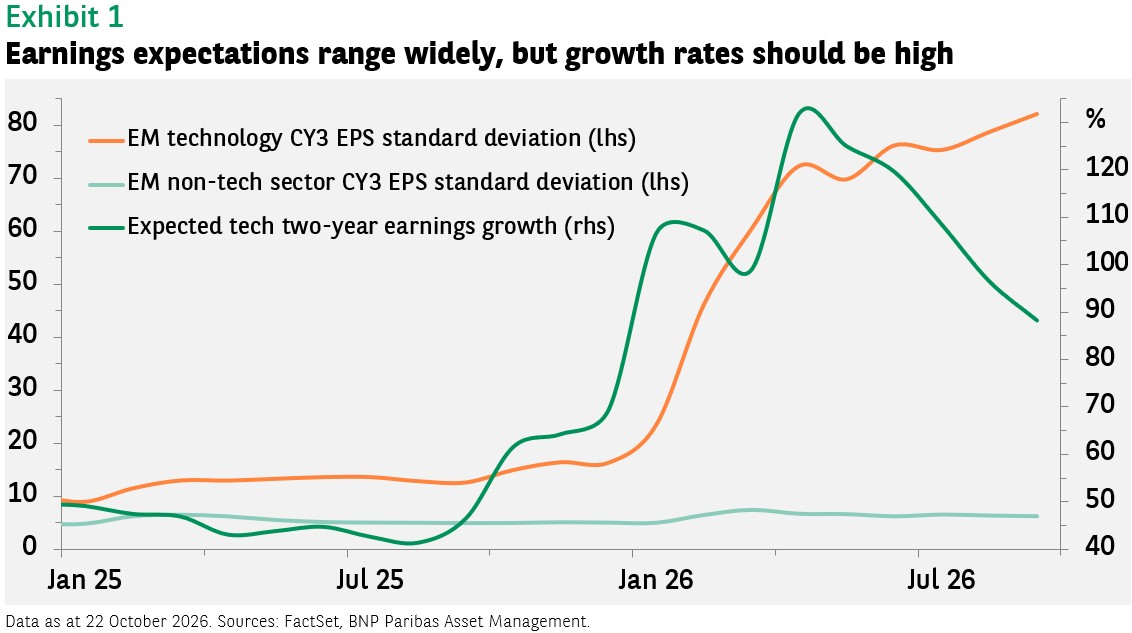
The consequence of the current high degree of uncertainty is that any marginal information can lead to a big change in the forecast for corporate profits, which can then lead to a big change in the stock price.
The key factor for investors with a longer-term time horizon is that the earnings growth in the years ahead should nonetheless be significantly positive; current forecasts for the next two years are near 90%. If in the end it turns out to be some (modest) percentage greater or less than those forecasts is secondary.


