
What do you need to know?
The European Central Bank raised its benchmark interest rate by 25 basis points to 2.5% and cautioned that the Middle East conflict is set to prolong inflationary pressures. It revised up its 2027 and 2028 inflation expectations to 2.5% and 2.1% from 2.3% and 2.0% respectively. However, it also increased its economic growth expectations for the bloc to 0.9% for 2026 and 1.4% for 2027, from 0.8% and 1.2% respectively. New data last week showed second quarter Eurozone GDP growth came in at 0.6% compared to 0% growth in Q1.
Around the world
China announced a 360-billion-yuan ($54 billion) support package for its banking and insurance sector to bolster the country’s financial system and help boost economic growth. The money will be injected into eight state-owned banks and insurance companies, according to reports, strengthening their ability to absorb external shocks while also providing support for the real economy. Elsewhere, Japan’s Q2 GDP growth was revised up to 1.4% (annualised) from the earlier estimate of 1.1% but remained below Q1’s 1.8% rate.
Figure in focus: 5.9 million
US employment is projected to grow by 3.5% between 2025 and 2035 – adding some 5.9 million jobs – but markedly below the 10.9% recorded over the previous decade, according to a US Bureau of Labor Statistics report. The utilities sector is projected to have the fastest job growth of all major industry sectors, and nearly all the growth is expected to come from electric power generation, transmission, and distribution due to rising demand for electricity, including for artificial intelligence. While retail is predicted to lose about 27,500 jobs – as e-commerce limits employment in stores – growing online purchases are expected to bolster expansion in transportation and warehousing.
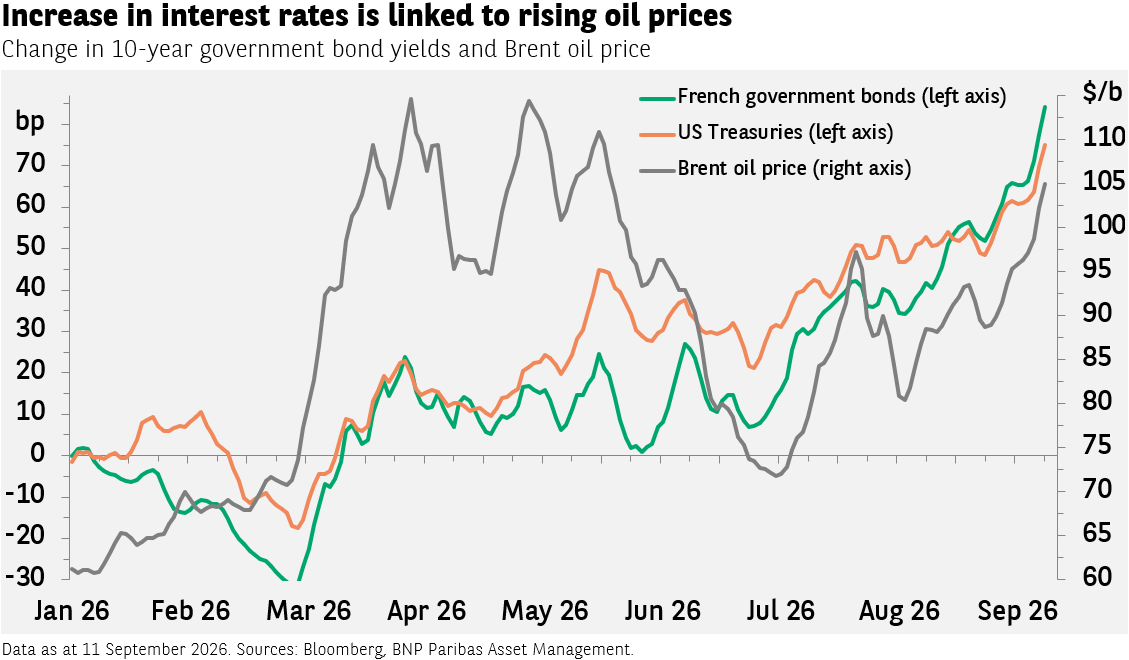
Chart of the week
Economists are increasingly worried about rising government bond yields. Many countries have large budget deficits and are plugging the hole by issuing more debt. This can lead to higher yields, meaning higher interest payments and less money for governments to spend on public services. Many developed countries’ finances are in bad shape, and the upcoming French elections risk exacerbating the situation due to promised spending increases. The impact of oil prices remains critical, however. While yields have risen since April’s $124 peak, oil prices are still elevated due to the Iran conflict. Should the situation improve and oil prices return to pre-war levels, government bond yields would likely drop as well.
Words of wisdom:
Orange bonds: Within the sustainable bonds’ category, the most common types are green, social, and sustainability-themed vehicles. But newer subcategories are emerging – such as blue bonds which focus on water ecosystems. One of the newest types is orange bonds where the proceeds raised are used to finance projects supporting gender equality and inclusion. The name is a reference to the United Nations Sustainable Development Goal 5, which aims to “achieve gender equality and empower all women and girls” and is represented by the colour orange.
What’s coming up?
Central banks will be in focus this week. On Wednesday the US Federal Reserve convenes to set interest rates. At its July meeting, it maintained rates at 3.50%-3.75%, though three of the 12-member committee opted for a 25-basis-point hike. The Bank of England and Bank of Japan hold their respective policy meetings on Thursday and Friday – both kept rates on hold in July. In terms of economic data updates, on Wednesday the UK issues its latest inflation numbers, with the Eurozone and Japan following up with their own inflation reports on Thursday and Friday respectively.


