
What do you need to know?
The Organisation for Economic Co-operation and Development now expects the global economy to grow 2.9% in 2026, slightly up on its previous forecast of 2.8%. However, it revised down its 2027 GDP projection to 3.0% from 3.1%. The OECD said inflation and higher interest rates will weigh on growth momentum in the near term, but robust artificial intelligence-related activity, and the expected easing of energy prices should help strengthen activity through 2027. It cautioned that further disruptions to energy supply from the Middle East conflict or extreme weather could also impact growth.
Around the world
US shares gained further ground last week as the US and China extended their trade war truce. A technology sector rally helped drive the Nasdaq index to a fresh high – over the week to Thursday’s close the tech-heavy index was up by 2%, while the S&P 500 rose by 1%.* However, the Dow Jones and European indices were down. Better-than-expected business data – the US flash Purchasing Managers’ Index for September rose at its fastest pace in over five years – raised concerns over further Federal Reserve interest rate hikes, prompting Treasury yields to climb to multi-decade highs.
* Source: FactSet, in US dollar terms. Data as of 24 September 2026
Figure in focus: 33%
Electricity could cost-effectively meet 33% of the world’s energy consumption by 2035, up from 23% today, according to a new report from the International Energy Agency. Electrification is helping countries strengthen energy security, boost competitiveness and reduce emissions, the IEA said. The analysis came ahead of the United Nations General Assembly where Secretary-General António Guterres called for clear timelines for the world to move away from fossil fuels.
Chart of the week
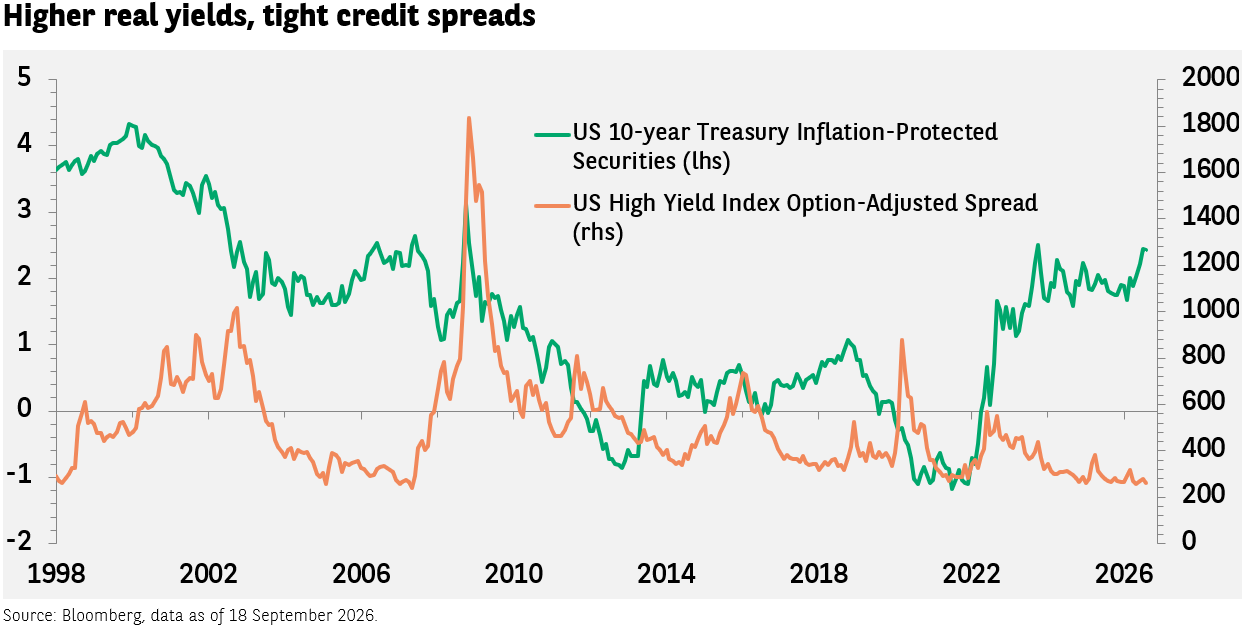
This year’s sharp rise in real yields (bond yields adjusted for inflation) has had little, if no, effect on the extra premium investors demand to hold corporate bonds (i.e. credit spreads). While this is somewhat reminiscent of the so-called Wall of Money period consisting of high levels of liquidity and cheap capital that ended with the 2008-2009 global financial crisis, we cannot compare today’s spreads with past levels. One reason is the significant improvement in the high yield universe’s credit quality. Another has to do with the current technological change, which is shifting the neutral interest rate – the theoretical rate that keeps an economy stable – higher, thanks to an economy-wide productivity shock.
Words of wisdom: Planetary boundaries
A term which defines nine critical processes and their limits in the maintenance of a stable and resilient Earth system. A new report from the Potsdam Institute for Climate Impact Research found that the seven planetary boundaries that have already crossed the “safe operating space” are now at their highest recorded levels of transgression. Only two – stratospheric ozone depletion and atmospheric aerosol loading – have improved over the last decade. It warned “the window of opportunity to act and avoid irreversible change is narrowing, but it is still open”.
What’s coming up?
On Tuesday the Reserve Bank of Australia convenes to set interest rates while the eurozone publishes its latest economic and industrial sentiment measures. The US and UK each report a final estimate of second quarter GDP growth on Wednesday. Thursday sees the Bank of Japan publish its Summary of Opinions, outlining its current views on economic activity and monetary policy. On Friday, the eurozone publishes flash inflation figures and the US updates on jobs data.


